Tampilkan postingan dengan label Advice. Tampilkan semua postingan

Obamacare insurer expands, but big questions loom as rate deadline hits, GOP pushes health plan

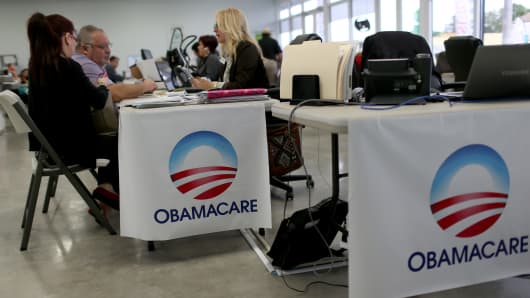
A couple enrolls in Obamacare with an insurance agent in Atlanta.

While Republicans in the Senate are getting ready to unveil their health reform bill, insurers on the Obamacare exchanges have been revealing their plans for next year ahead of Wednesday's deadline to file initial 2018 rate requests.

"This may be the most closely watched rate filing since the first year of the ACA marketplaces," said Katherine Hempstead, a senior advisor at the Robert Wood Johnson Foundation. "They are rightly seen as important signals about the viability of the individual market in its current form."

Four-year-old health insurance start-up Oscar Health has decided that the Obamacare markets are still viable, and is planning to expand coverage next year.

"We are spending 98 percent of our days thinking about 'what does the product look like? What network can we build?'… and 2 percent worrying about the regulatory framework," Oscar Health CEO Mario Schlosser said.

Oscar is planning on launching in two new states next year, announcing Wednesday morning that it will offer coverage in the greater Nashville area in Tennessee, in addition to its new joint venture to offer a plan with the Cleveland Clinic in northeast Ohio.

But Oscar's expansion won't extend to some of Ohio's potentially bare counties, in the southeastern part of the state, where Anthem's decision to withdraw from the state's Obamacare exchange next year could leave some markets with no insurer.

"We've really got to make sure that our unique strategy around how we build networks … also works," said Schlosser.

Centene announced that it would be expanding coverage into Ohio and Missouri, but a spokeswoman for the insurer said it is still working out which parts of those states it will cover

As of Wednesday's deadline, roughly two dozen counties in northwest Missouri had no insurers filing to provide 2018 coverage, according to an analysis by researchers at the Kaiser Family Foundation.

"It is entirely possible that Centene or other insurers could move into some counties that appear to be at risk of having no insurer," said Cynthia Cox, the foundation's associate director. "Consumers in these counties shouldn't worry too much yet, as there is still time for insurers to change their service areas. Companies don't get locked in until early fall."

In Washington state, two counties had been facing no insurer coverage, but earlier this week Premera Blue Cross reportedly reversed course, and agreed to remain in one of those counties, Grays Harbor. 

"I really feel for a number of our insurance companies, because it's not that they don't want to be participating," said Michael Marchand, chief marketing officer of the Washington Health Benefit Exchange. "It's the uncertainty in the marketplace."

Insurers in the state are asking for a 22 percent increase for next year on average. States insurance officials say the carriers are trying to price in risk that they may not be reimbursed by the Trump administration for cost-sharing reduction subsidies that lower out-of-pocket costs for lower-income enrollees.

"As a result, we're seeing an increase in premiums because it's essentially the insurance companies hedging their bets that there may be the potential for them to have to pick up that CSR costs," said Marchand, referring to the subsidies.

For state regulators and insurers, the question of funding for the subsidies will be a key issue that will hang over rate reviews and the final push toward open enrollment just over four months from now.

"If a way is not found to pay them for 2018 there will losers, but no winners," said Hempstead. "The biggest losers will once again be the unsubsidized customers, who will be exposed to the entire premium increase with no relief."

For that reason Oscar's Schlosser is convinced the Trump administration and Republicans will find a way to fund the payments next year.

"From a common sense perspective, I really think when the dust settles, there will be a stable individual market. And compassion and reason will prevail on that," he said.

Life Insurance Basics


Unfortunately, death, like taxes, is a certainty for us all. Sure that sounds depressing, but it could be a whole lot worse– like leaving the family behind with an unpaid mortgage, a mountain of bills and those mind-numbing tuition costs.

Making sure your loved ones are financially provided for after you’ve unexpectedly shucked the mortal coil is the motivation behind life insurance policies. Life insurance provides a “death benefit” which can be used to take care of that mortgage, the bills… even the kid’s tuition. In effect, this policy substitutes for income lost due to the insured’s untimely death.
Two basic coverages are available:

Term. This protection typically extends from one to thirty years, paying a death benefit only if you die during the term of coverage. Term premiums are usually more affordable than the alternative (permanent insurance) allowing more bang for the buck and putting the coverage where it’s most needed– when the kids are young. The cost of term does go up, however, every time the policy is renewed, which could become cost inefficient once you reach those golden years.

Permanent. The premium for this insurance is typically locked at the age when the policy is first written, which means your cost remains constant for the duration (as long as you stay current). Although permanent coverage costs more than term, the cost doesn’t increase with age– a nice hedge against inflation. These policies also accumulate cash value as they mature, and the insured can borrow against that cash value in the form of low-interest loans.

Insurance experts say the amount of insurance you’ll need should be based on how much money you make. The rule of thumb suggests protection five to eight times annual income, but make sure to discuss all coverage options with your agent. When figuring coverage you should consider your family’s needs once you’re gone, including all ongoing costs your spouse and children can expect down the road. Remember to factor in those immediate after-death expenses like medical and funeral bills. Also ask about mortgage insurance, which is coverage that pays off the note if you pass away before you’ve completed all payments.

Life insurance is sold through agents or directly from the company– including over the Internet. But no matter where you make your purchase, don’t forget to solicit and compare price quotes from at least three different companies.

Good luck, stay healthy… and eat your vegetables.

Life Insurance FAQs – Frequently Asked Questions


  1. Should I buy term life or permanent life insurance?
  2. What is the difference between whole life and universal life insurance?
  3. What is the advantage of level term life insurance vs. yearly renewable term life insurance?
  4. What riders/options/features are available on life insurance policies?
  5. What is involved in the life insurance application process?
  6. When does my life insurance coverage begin?
  7. How is an applicant classified?
  8. What if I receive a higher rate than I applied for on my life insurance policy?
  9. What is the tax treatment of life insurance death benefit proceeds?
  10. Should I purchase life insurance on my spouse?

Should I buy term life or permanent life insurance?

The type of life insurance you need is dependent upon your particular needs. Term life insurance is appropriate and more cost effective for temporary needs, which may be a period of one to thirty years. On the other hand, permanent life insurance is better for permanent or long term needs. In some cases, a mix of both term life and permanent life insurance may be suitable.
What is the difference between whole life and universal life insurance?

Whole life insurance and universal life insurance are both types of permanent life insurance; however, universal life has flexible premiums and an adjustable death benefit. Whole life insurance premiums are fixed level and the death benefit is not adjustable. Another difference between these two types of insurance is the cash value of a universal life insurance policy is interest sensitive. If interest rates go up, so will the cash values. A whole life insurance policy’s cash value is not very interest sensitive
What is the advantage of level term life insurance vs. yearly renewable term life insurance?

The advantage of level term life insurance is that the premiums remain level over a specified period of time. Yearly renewable term life insurance has a lower initial premium; however, the premium rises each year. Yearly renewable term life insurance is only cost effective for a few years because of the rising premiums. If you need term life insurance protection for more than a few years, then a level term life insurance policy can cost less.

Please carefully consider the length of the level premium period that will suit your needs. For example, if the primary purpose of the death benefit is to provide income to support very young children and/or to fund college education expenses, a 20-year level premium might be appropriate. If these children are already in their young teens, you may need only a 10-year level premium (longer level premium policies are more expensive).

After the level premium period expires, most policies require you to requalify with medical underwriting in order to receive a favorable premium. If you do not or cannot requalify, the premium typically rises dramatically after the expiration of the level premium period.
What riders/options/features are available on life insurance policies?

The following riders/options/features are available with some life insurance policies:
Conversion Feature – allows the owner of a term life insurance policy to exchange (or convert) the policy to a permanent life insurance plan (whole life or universal life) without evidence of insurability.
Spousal Discount – if both a husband and a wife or two business partners purchase life insurance at the same time, then a discount will be deducted each year from the total cost of both policies.
Children’s Insurance Option – provides term life insurance coverage on each child of the insured’s family.
Accelerated Death Benefit – accelerates the availability of a portion of the death benefit if the insured is diagnosed as terminally ill by a licensed physician (must be terminal within 12 months).
Waiver of Premium Option – the insurance company will continue to make your life insurance premium payments if you become disabled.
Accidental Death Benefit Option – an additional death benefit will be paid if you die by accidental means.
Guaranteed Purchase Option – guarantees that you may purchase additional life insurance in the future without proof of insurability
What is involved in the life insurance application process?

The life insurance application process consists of submitting an application and a medical exam to the life insurance company. It may also be necessary for the life insurance company to contact you for a brief telephone interview.

The medical exam can be scheduled at your home or work and is paid for by the life insurance company. The exam typically consists of medical history questions, blood/urine specimen, blood pressure/pulse readings, and height/weight readings. Sometimes additional requirements are necessary, such as an EKG. It is recommended that you schedule your exam early in the morning because test results are often better at this time.

Once we receive your completed life insurance application, it will be submitted to the insurance company. Underwriting usually takes approximately 4-8 weeks. Assuming your life insurance policy is approved, we will send it to you.
When does my life insurance coverage begin?

Your life insurance coverage begins once the policy has been issued and all of the delivery requirements have been returned to the insurance company. Delivery requirements may include a premium payment, statement of health, delivery acknowledgement form or amendment of application.

Temporary coverage during the underwriting process may also be available with some insurance companies. In cases where temporary coverage (also called conditional coverage) is available, coverage begins once the completed application has been returned to the insurance company with a premium payment and you have completed the medical exam. The coverage is contingent upon you qualifying at the rate you applied for and a few other factors. Read the conditional receipt of your life insurance application for additional information.
How is an applicant classified?

The life insurance company uses factors such as personal medical history, family medical history, financial situation, and sometimes avocation and occupation to place an applicant in a specific rate class.
What if I receive a higher rate than I applied for on my life insurance policy?

If you apply for life insurance through ReliaQuote and you receive a higher rate on your policy or you are declined, we will automatically shop your life insurance coverage with other life insurance carriers. First, we will identify (on a “no names” basis) other insurance companies that may be more liberal given the reason you received a higher rate or were declined. Then (again, without disclosing your name) we will send each of these insurance companies the information they need to make an estimate of the rate for which you would most likely qualify based on their particular underwriting criteria. Once we have received the alternative rates, you will be contacted by a ReliaQuote Customer Service Representative who will explain your options. You will have the opportunity to stay with the original life insurance carrier you applied with or submit an application to the alternative carrier who may offer a better rate.

One of the benefits of this unique service is that you do not have to complete another medical exam or application for us to shop you with other carriers! We simply use your first application and medical exam results.
What is the tax treatment of life insurance death benefit proceeds?

Life insurance death benefit proceeds are generally not subject to income taxation provided they are paid in a lump sum; however, there are a few exceptions to this rule. If a settlement option is used other than the lump sum option, then the interest earned on the principal death benefit is taxable.

Although life insurance proceeds are generally exempt from income taxation, they are subject to estate and inheritance taxes. For more information on estate and inheritance taxes visit the estate planning section.
Should I purchase life insurance on my spouse?

In most cases, yes. At the very least, if your spouse contributes to the family’s annual income then adequate protection would be needed to supplement his or her income should he or she die. If your spouse does not have an income but is a homemaker, then life insurance protection may be needed to cover daycare and other costs associated with the loss of a parent. Use our life insurance needs calculator for additional help on estimating the amount of life insurance your spouse needs.
Possible Aetna Move Prompts Focus on Urban, State Policies in Connecticut


Connecticut officials are again re-examining how they can dissuade companies like General Electric and now possibly insurance giant Aetna from relocating to places considered more innovative.

A string of state budget deficits, state and local tax policies, as well as hefty state debt obligations are all being blamed for why Aetna and others may be looking to places like Boston, Mass., to move their headquarters and attract talent. But many also are looking at the condition of Connecticut’s cities and how they measure up against the competition in other states.

“Our inactivity, our unwillingness to come up with an overall goal for our urban centers in the state of Connecticut is yet again costing us dearly,” said Democratic Speaker of the House Joe Aresimowicz on Thursday, the day after Aetna’s chief executive announced his company is in negotiations with several states to move its headquarters out of Hartford, where it has been based for nearly two centuries. He said major employers “want to know what our plan is” for Connecticut’s cities, adding how lawmakers may pass legislation this session that could lead to more state aid and stronger oversight of city spending.

Aetna’s possible move comes despite Connecticut Democratic Gov. Dannel P. Malloy offering the company financial incentives to stay in Connecticut. Aetna has not responded to the offer.

Mark Bertolini, Aetna’s chief executive officer, said the insurer remains committed to its roughly 6,000 Connecticut-based employees and its Hartford campus. However, he said the company wants to broaden its access “to innovation and the talent that will fill knowledge economy-type positions.” His comments come about a year-and-a-half after GE announced it would move its corporate headquarters from suburban Fairfield to technology-rich Boston, which chairman and CEO Jeff Immelt said fit the company’s ambitions as an innovation leader.

Hartford Mayor Luke Bronin said “losing Aetna’s flag” would be a blow to the state and greater Hartford. The Democrat said the state must now act boldly.

“I think the decision that Aetna seems poised to make, reinforces the argument that we’ve been making for the better part of a year, which is that if Connecticut wants to remain economically competitive, we have to be a place that has strong and vibrant cities – strong and vibrant metropolitan areas, where companies can attract talent and retain talent,” said Bronin, who has pushed for greater regional cooperation to bolster Hartford.

Oz Griebel, president and CEO of the MetroHartford Alliance, a regional business group, acknowledged Aetna is one of the state’s most valued employers and the image of the company moving its corporate headquarters elsewhere has a “psychological impact” on the state. But he stressed that major investments have been made in Hartford and other Connecticut cities. Steps are being taken to address the state’s fiscal obligations, such as employee retirement costs.

While the state’s cities are not as large as Boston or New York, he said Connecticut continues to have an educated and innovative workforce.

“The asset base here is very strong,” Griebel said. “Our job is to promote that asset base.”

Susan Winkler, executive director of the Connecticut Insurance and Financial Services Cluster, an association of 32 insurance and financial services industry leaders, said even if Aetna moves its headquarters, Connecticut will remain the insurance capital of the world.

“Connecticut has a rich history of insurance practice,” she said. “Our workforce is really second to none. We have the most insurance jobs, the most actuaries. We write the most premiums. We are the insurance capital and that’s not going away.”

The state also has a healthy pipeline of labor into the insurance and financial services industries from colleges and other sources, Winkler said. At 2.7 percent, Connecticut ranks first nationally in insurance carrier employment as a percentage of total employment. The average wage for nearly 59,000 insurance carrier jobs is more than $83,936, according to 2016 state industry report.

Associated Press Writers Dave Collins and Pat Eaton-Robb contributed to this report.

Moving Insurance Coverage Options for your Move


Occasionally, items can get lost or damaged in the moving process. So, in choosing the proper coverage to protect your possessions during the move, make sure to assess your needs before finalizing your protection.

or
The three most common types of moving coverage are:

Basic Liability

Your items are usually covered at 60 cents per pound, per item – regardless of their actual value. So whether it’s your pens or your precious family heirlooms you’ll be covered based on the weight of those items.Cost: Usually Free

Declared Value Protection

An improvement over basic coverage, Declared Value Protection offers coverage for the replacement value of lost or destroyed items, minus depreciation. If your three year old TV is smashed during the move, the moving company won’t replace it with a new one. They may try to repair it to its original condition or you will be given the fair market value of the three year old TV.
Cost: Usually based on the declared weight, lump sum or per-pound value of your shipment, subject to certain minimums.

Extra Care Protection/Customer Transit Protection (Canada)

A high level of protection. If an item is lost or destroyed, most companies will offer the full replacement cost – regardless of the item’s depreciation. Ask about this option at full value or with a deductible.
Cost: Usually dependent on the value of the declared shipment.

Regardless of which plan is most appropriate for your circumstances, remember to ask your moving counselor to explain each alternative carefully. It’s also a good idea to review your homeowner’s insurance policy to determine whether or not it provides coverage for any especially valuable items such as crystal, antiques or collectibles during a move.

Regulator in China Takes Aim at Anbang Insurance Group


The Beijing headquarters of the Anbang Insurance Group. A Chinese regulator has banned the company from selling two of its investment products. CreditJason Lee/Reuters


SHANGHAI — A Chinese regulator announced on Friday that it had taken disciplinary measures against the Anbang Insurance Group, a financial behemoth that has tried to invest tens of billions of dollars overseas, for the improper sale of two investment products.


The moves by the China Insurance Regulatory Commission come against a backdrop of broader worries about the country’s financial system, in addition to ones about the insurance industry.


President Xi Jinping told Politburo members last month that China should place a strong emphasis on financial stability as a pillar of a strong economy, Xinhua, the state-run news agency, reported.


Many foreign economists and investors on Wall Street have expressed misgivings about China’s rapid accumulation of debt, particularly at state-owned enterprises, since the global financial crisis in 2008 and 2009.


Chinese regulators began stepping up their scrutiny of banks several years ago, and they have been discouraging some aggressive lending and money-raising programs. Partly in response to that, real estate developers and others who needed to borrow large amounts of money began turning to insurers, which rapidly expanded their financial activities and raised the money to do so by selling a wide array of often speculative investment products.


The State Council, China’s cabinet, announced separately on Friday the dismissal of the chairman of the insurance regulatory commission, who has been the subject of a corruption investigation. The government has not linked that investigation to Anbang, however.


This week, the insurance regulator said it was barring Anbang from selling two of its investment products.


One, the Anbang Longevity No. 5 Annuity, had been presented to regulators as a long-term investment. But the commission said that it was effectively a two-year investment that should have been subject to more stringent regulations on short- and medium-term investments.


The other banned investment product, Anbang Endowment Insurance, was put on the market without an actuary’s signature, the commission said.


In an uncommonly sweeping warning to the insurer, the regulator concluded its announcement by telling Anbang that it should pay “high attention” to its full range of investment products and “fix the work on product development and management in strict accordance with supervision policies and requirements.”


The investment-product bans and the broad admonition were part of a direct order to the company that was dated on Thursday and posted on the commission’s website on Friday.


Anbang said that it had no immediate comment on the commission’s order. Chinese regulatory decisions typically take effect immediately, particularly if published for the general public to see, and are nearly impossible to appeal.


The State Council announced separately on Friday that Xiang Junbo, the chairman of the China Insurance Regulatory Commission, had been removed from office. No successor was announced.


Mr. Xiang’s dismissal had been widely expected after Chinese anti-corruption investigators announced a month ago that they had investigated him over “severe violations of discipline.” The government did not link that inquiry and his dismissal to Anbang.


Mr. Xiang has not commented publicly about the investigation since it was announced. The targets of anti-corruption inquiries are typically held in custody and are sometimes subjected to harsh interrogation.


Anbang has been a leader among insurers when it comes to using so-called wealth management products, a class of lightly regulated investments that promise higher rates of return than conventional investments, but that also carry higher risks that may or may not be disclosed.


Wealth management products also tend to promise a quick payback period. But the issuing companies are exposed to liquidity risk if investors ask for their money back instead of reinvesting. The liquidity risk is particularly high if the issuer has put its money into long-term projects that cannot be sold quickly to raise cash.


Many small- and medium-size banks are increasingly raising money for loans, bond purchases and other investments by issuing wealth management products, and even some largely unregulated companies have begun issuing wealth management products.


Anbang came to international prominence in January when its chairman, Wu Xiaohui, met with Jared Kushner, President Trump’s son-in-law and close adviser, at the Waldorf Astoria Hotel in New York. The two met to discuss the possible sale to Anbang of a Kushner family stake in the redevelopment of a Manhattan skyscraper, 666 Fifth Avenue. But those talks ended in March as the proposed transaction became increasingly divisive on both sides of the Pacific.


Anbang bought the Waldorf Astoria for nearly $2 billion in 2014, among $16 billion in overseas acquisitions it made over the past few years. The company, started 13 years ago, has assets of almost $275 billion, a growing portion of which comes from the sale of wealth management products instead of insurance policies, according to Caixin, a Chinese investigative magazine.


Caixin accused Anbang last Saturday of having a shareholder structure that “is like a maze,” and it questioned the appropriateness of capital injections from companies linked to Mr. Wu.


Follow Keith Bradsher on Twitter @KeithBradsher.

Kreidler’s office helped thousands of Washington residents in 2016

Today, we published our 2016 annual report, which gives an overview of the work our office did last calendar year.
2016 annual report WA OIC

  Some highlights:
  • We regulated nearly 2,400 companies and 164,000 licensees.
  • We collected $534.7 million in premium taxes from insurance companies.
  • Of that amount, $521 million went to the state general fund to support K-12 education, higher education, human services and general government operations. 
  • We fielded nearly 8,000 consumer complaints and helped recover $11.3 million related to billings and claims.
  • Answered more than 67,000 calls to our consumer hotline.
  • Helped more than 83,000 people with one-on-one health insurance counseling through our SHIBA program.
Read the full report.

Funeral insurance options for everybody in the World


We get that it's not the cheeriest topic on the block, but covering the cost of your departure from the earth is worth some research.
Like the name suggests, funeral insurance is designed to cover the cost of your funeral. Sounds easy enough, but we found:
  • you can end up paying more in premiums than the value of the funeral cover
  • pre-paid funerals, funeral bonds and life insurance are better options.
According to actuaries Rice Warner, taking out funeral insurance at age 65 could mean your premiums almost add up to the costs of four funerals if you live until 91.
So what are all the options?

Funeral insurance

If you go down this route you'll usually make a regular contribution until age 90, after which time cover continues for free. The benefit amount is either fixed or increases over time, and you're usually only covered for accidental death for the first couple of years. An age limit of between 18 and 79 years normally applies – the older you are, the higher the premium.

Risky business

  • Premiums can be fixed or increase each year, and can vary according to your gender and whether or not you smoke.
  • If premiums are not fixed you often won't know how much they increase in subsequent years.
  • If you stop paying your premium, you'll no longer be covered and in most cases won't receive a refund.
  • Premiums can add up to more than four times the cost of a funeral.

Call for reforms to funeral insurance

In 2013, CHOICE joined 10 other consumer and pensioner advocacy groups, including the Consumer Action Law Centre (CALC), in calling for reforms to funeral insurance in Australia. 
In response to this, Hollard Insurance has released their "Guaranteed Funeral Insurance" product, which promises that:
  • premiums will never increase
  • premiums will actually reduce by five per cent after every continuous five years of the policy
  • the total premiums paid will never be more than the benefit paid – that is, they will pay the higher of the benefit amount or the total premiums paid since product was taken out.
"It's positive that there's now a funeral insurance product with improved terms", says Matt Levey, CHOICE Director, Campaigns & Communications. "But our advice is still that consumers look at options that can be more affordable and can give them better value for their money such as life insurance, pre-paid funerals or simply using a separate savings account."

Pre-paid funerals

The pre-paid option's a better choice, and covers all or part of your funeral, usually at today's prices. The services you pay for are covered when you die, regardless of how much they cost at the time.
There are a few ways to fund pre-paid funerals.
  • Small contributory funds: You make small, regular payments for part or all of a funeral service with a particular funeral director. Conditions vary between funds.
  • Pre-purchased products: You pay for a cemetery plot, wall niche or place in a memorial garden, usually directly from the cemetery or crematorium.
  • Pre-paid funeral plans: You choose the type of funeral you like and pay for it in full. Or make a deposit and pay installments over a fixed period. Few plans offer a refund if you cancel – check this before committing.

Funeral bonds

Funeral bonds are usually offered by friendly societies or life insurance companies, and require you to make a lump-sum payment or pay by installments. The money is invested and can only be used to cover your funeral. The funeral bond can be in your name or joint names. If you go for the latter, the benefit is normally paid on the death of the first joint owner.

Do you need another Income protection insurance policy?


Income protection insurance is a type of life insurance that provides an income if you're unable to work. It's often overlooked, because being out of work is not the cheeriest thing to think about. The insurance payment kicks in after a certain period and covers a portion of your income. And, like many things in life, it's not as simple as it sounds.
There are two main types:
Agreed-value insurance, the most expensive option pays out a benefit agreed to reflect your income at the start of the policy. This type's not affected by any fluctuations in income - kind of like 'agreed value' car insurancecover, rather than market value.
Indemnity value policiesare cheaper and more common. These verify your income at the time of making a claim and may adjust your benefit accordingly. So your payout salary can depend on things like maternity leave, working part time or becoming unemployed.
Indemnity value policies provided by super fundsare the cheapest, with fewer features and less flexibility. They may also be limited to a shorter time period.
How long does it last?
This depends on how much you want to cough up for better contract terms. The more you pay for the insurance, the longer they'll pay you in the case of illness or injury. Policy terms range widely, from two to five years, or up to age 60 or 65.
Do I need income insurance?
It depends. Income protection policies are designed to meet the costs of 'living', rather than ensuring family members receive a payout after your death. If you're young and single with no dependents and limited fixed expenses, income insurance is useful. If you're a family type who needs to look after loved ones, life insurance may be a better bet.
So how much cover do I need?
Here you'll need to do some homework. Income protection covers roughly 75% of your income if you're sick, injured or unable to work. To get the best cover you'll need to budget your standard costs - like monthly mortgageor car loan payments – along with any dependents you want to provide for, plus the cost of managing any investment assets. This will help you decide what level of cover you need.
How much will it cost me?
Shop around and compare cover and prices - they differ greatly. Premiums are set depending on:
  • age (premiums may increase or cover may decrease as you get older)
  • gender
  • health and pre-existing conditions
  • whether or not you smoke
  • occupation (for example, a manual laborer pays different premiums to an office worker)
  • the time you choose to wait before receiving payment
Stepped or level income protection insurance premium… say what!?
The fun doesn't end there. Now we'll talk about different types of premiums.
  • A stepped premium starts out cheaper, but increases over time.
  • Level premiums are constant but vary depending on age at entry. They start out more expensive, but after 10 to 12 years of cover they're the cheaper option.
  • If you plan on sticking with the same provider, a level premium is better in the long term.
  • If you like to shop around, a stepped premium is wiser.
The tips and traps of income protection insurance
This isn't an exhaustive list. Before committing to a policy you should compare product disclosure statements. You might also consider getting professional financial advice.
  • When taking out a policy, ask these key questions: What's covered? What's not covered? How much will I be paid after a claim? What will the insurance premiums cost now and later?
  • Consider getting a policy with index-linked premiums and cover so you know it will keep up with inflation.
  • Consider a non-cancellable policy, otherwise companies may reassess your health or other factors on each renewal, possibly raising your premiums or refusing to continue cover.
  • Look for a policy with Guaranteed Future Insurability, a benefit that allows you to increase your level of cover without further underwriting. This is important if your circumstances change due to things like buying a home or having a child.
  • Offset clauses allow insurers to reduce payouts if you have other income (for example, sick pay or Centrelink benefits). Check the relevant section of the policy for details.
  • With group insurance provided through super: the agreement is between the fund trustee and insurer. This may make the claim and payout less straightforward. Check the waiting period (how long before you receive payment, often 30 or 90 days) and the benefit period (for how long payments will be made — typically two years or sometimes until your normally expected retirement age).
  • Some policies pay out if you're unable to perform your normal occupation. Others only pay if you can't perform any occupation for which you're suited by education, training or experience. Look out for policies that pay if you're unable to perform your regular occupation.
Watch those terms
When taking out any insurance policy, you should check carefully the terms and conditions. You should also check the way the key terms of the policy are defined.
Nick, a farmer from Gloucester, found this out the hard way:
Nick had an income insurance policy with a large insurer. The policy was fine, but Nick had a not-so-typical income situation, because the money he made varied depending upon the success of the farm each year.
When Nick had an incident, the company refused his claim because they had defined his assessable income as being based on his taxable income. Sadly for the year in question, Nick had no taxable income. Instead, his income that year came from a legitimate repayment of money he'd lent to the family company in previous years.
Nick had seen no mention of 'taxable income' being the basis of assessing the insured's income. Luckily he was able to use an independent claims assessor to help negotiate with the insurer and eventually reach a compromise.
  • Our tip: It's important to read all the terms to make sure you're not caught out at a tough time.

Popular Posts